

The NRI’s Blueprint for 2026: SBI vs. HDFC Financing for Luxury Villa & Flat Acquisition in India
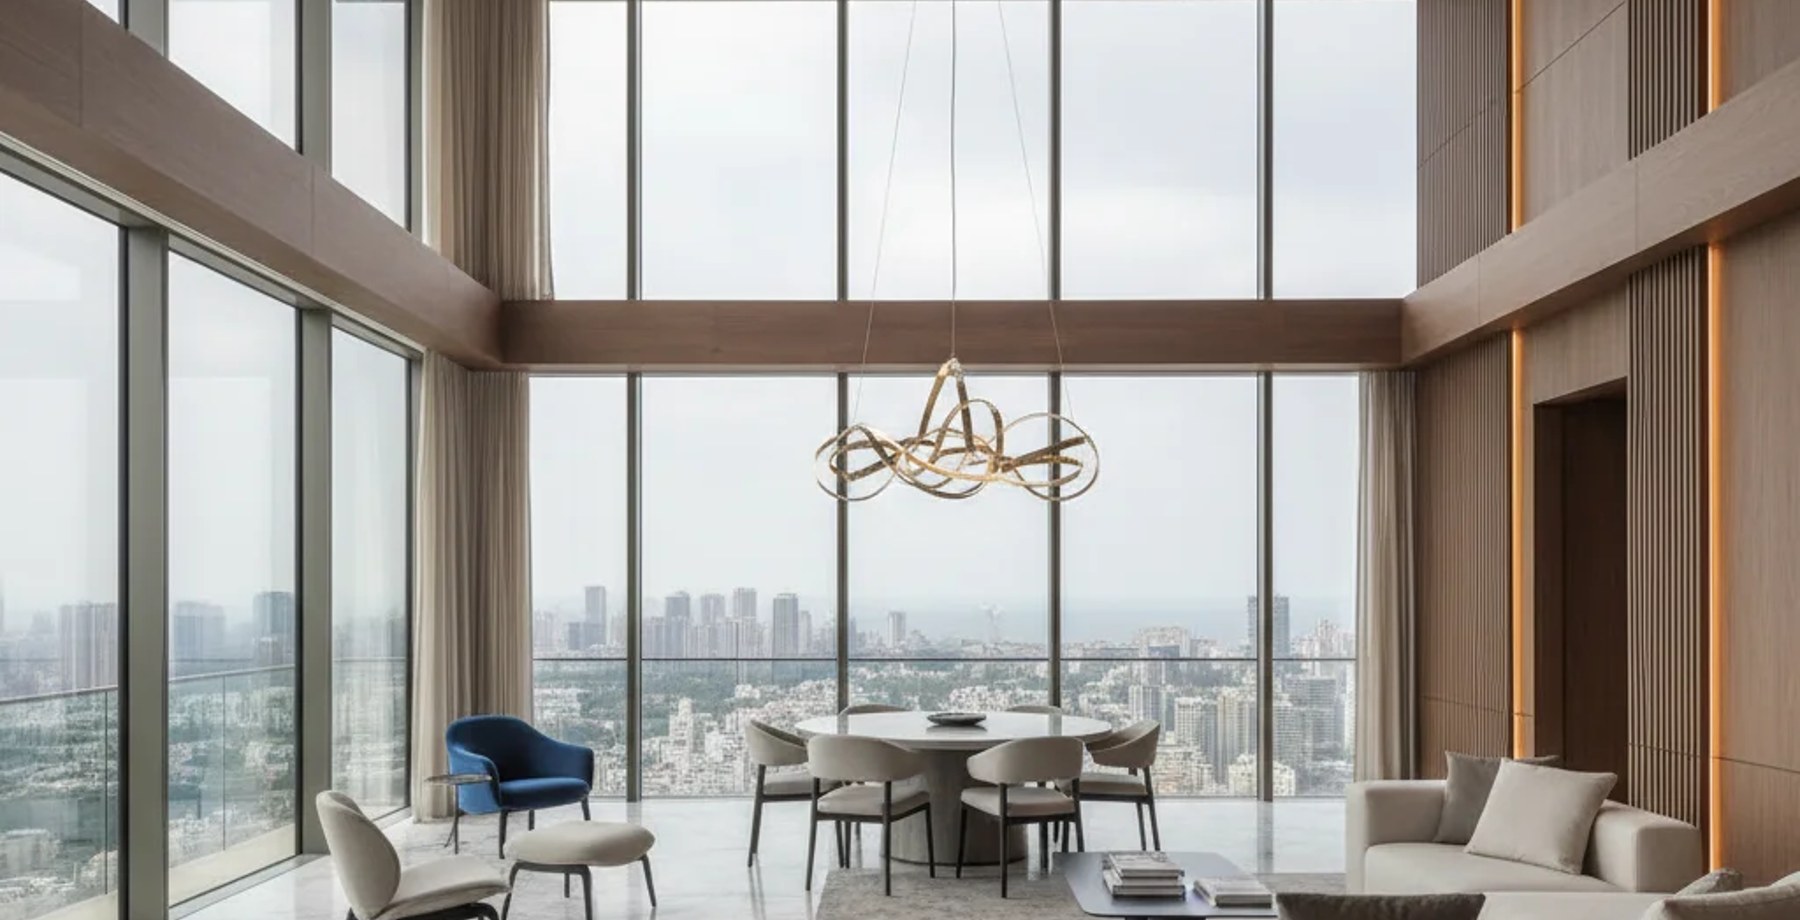
Table of Contents (7 sections)▼
Executive Summary: Capital Deployment in the Indian Luxury Market
or the Non-Resident Indian (NRI) or Overseas Citizen of India (OCI) seeking to acquire premium residential assets in India in 2026, the financial instrument is as critical as the architectural design. The acquisition of a luxury villa or high-end flat is not merely a transaction; it is a complex interplay of foreign exchange regulations (FEMA), banking covenants, and asset valuation.
This guide dissects the two dominant financial pillars for NRI real estate: State Bank of India (SBI) and HDFC Bank. While both institutions offer robust NRI home loan products, their structural differences in tenure, loan-to-value (LTV) ratios, and processing mechanics significantly impact the net present value of your investment.
Comparative Financial Architecture: SBI vs. HDFC (2026)
The following matrix outlines the critical financial parameters for NRI applicants as of Q4 2025/Q1 2026 projections. Note that while base rates are competitive, the effective cost of capital is determined by the spread over the Repo Rate and the specific LTV ceiling applicable to your loan quantum.
#### The "Luxury Threshold" Analysis For properties exceeding ₹10 Crore, HDFC Bank’s standard NRI home loan limit becomes a bottleneck. While HDFC may offer private banking solutions for higher tickets, the standard NRI product caps at ₹10 Cr. SBI, with its ₹15 Crore ceiling, remains the primary institutional lender for ultra-luxury villa projects in prime corridors like Mumbai, Bengaluru, and Delhi NCR.
Regulatory Protocols & Eligibility Framework
Under the Foreign Exchange Management Act (FEMA), NRIs and OCIs can acquire immovable property in India for residential purposes. However, agricultural land, plantation property, and farmhouses are strictly prohibited.
Key Eligibility Constraints (2026):
- SBI: 18 to 70 years.
- HDFC: 21 to 65 years.
- Implication: For younger NRIs (21-25), HDFC is accessible. For senior NRIs (65-70), SBI offers a wider window.
- ICICI Bank (for reference) publishes specific thresholds (e.g., USD 42,000/year for US-based NRIs).
- SBI & HDFC do not publish a rigid minimum income on their public NRI pages, relying instead on a holistic assessment of overseas income, credit history, and asset base. However, a benchmark of USD 500/month (SBI) or equivalent stable overseas income is generally expected.
- Both banks require a valid POA registered in India if the NRI cannot be physically present for the loan execution. The POA must be specific to the property transaction and loan signing.
Architectural Execution & Material Engineering
While the loan secures the asset, the value of the asset is determined by its architectural integrity and material specification. For luxury acquisitions, the following engineering standards are expected in 2026:
#### 1. Structural Envelope & Glazing
- Schüco System 70/80 SI: High-performance thermal break aluminum profiles are standard for luxury villas. This ensures energy efficiency and acoustic isolation, critical for high-density urban luxury flats.
- Low-E Insulated Glass: Double or triple glazing with Low-Emissivity coatings to manage solar heat gain, reducing HVAC load by up to 30%.
#### 2. Interior Finishes & Material Science
- Statuario Marble: For high-end flooring and cladding, Statuario marble from Carrara, Italy, is the benchmark. Its high contrast veining and durability make it ideal for living areas and master suites.
- SS316 Hardware: All door handles, faucets, and structural fittings must be Grade 316 Stainless Steel. Unlike 304, SS316 contains molybdenum, providing superior corrosion resistance against coastal humidity (critical for Mumbai/Goa properties).
#### 3. HVAC & Climate Control
- Daikin VRV (Variable Refrigerant Volume): Centralized VRV systems are preferred over split ACs in luxury villas. They offer zoned temperature control, lower noise levels, and a sleeker aesthetic by hiding ductwork within false ceilings.
Execution Timeline: From Offer to Occupancy
For an NRI purchasing a luxury property, the timeline is extended due to regulatory checks and international documentation.
- Verification of title deeds, RERA registration, and builder’s financial health.
- Architectural Review: Ensure the project’s material schedule matches the promised specifications (e.g., confirming Schüco glazing vs. standard aluminum).
- Submission of POA, overseas income proofs, and tax returns.
- SBI processing time: ~15 days. HDFC processing time: ~15 days.
- Bank-appointed valuer assesses the property. For luxury assets, this may involve specialized valuers for high-ticket items.
- Funds are disbursed directly to the builder’s account via inward remittance.
- Property registration is completed in India via POA.
Strategic Recommendation
- Choose SBI if: Your property value exceeds ₹10 Crore, you require a 30-year tenure to lower EMIs, or you wish to minimize upfront processing fees.
- Choose HDFC if: You are an OCI cardholder (explicitly eligible), your loan amount is under ₹10 Crore, and you value a slightly lower starting interest rate (7.45% vs 7.50%).
- Consider ICICI if: You have a high, verifiable overseas income (USD 42k+) and prefer a fully digital, online application process with clear published income thresholds.
Partner with ERENDERS for Architectural Excellence
Securing the loan is only the first step. Ensuring the property meets international luxury standards requires expert architectural oversight. At ERENDERS, we specialize in turnkey interior architecture and society redevelopment, ensuring that every material—from Statuario marble to Schüco glazing—is executed to the highest engineering standards.
Ready to acquire your dream property in India with confidence?
[Contact ERENDERS for Architectural Consultation & Project Management](https://erenders.in/contact)
Have a critique or feedback on this architectural concept? Join 1,200+ architects and 3D artists in the Roastitects Community Debate Arena.
JOIN ROASTITECTS DEBATE →Frequently Asked Questions
Technical Q&A from this article — answers expanded for depth and SEO.
Looking for more architectural research & spatial studies?
Browse full-width editorial essays, LOD technical specs, and audio folios in the Community Folio.
Just published
10 Stories to Know Right Now
3 stories
- 01ARCHITECTURE9 min reading timeOct 29, 2026BIM & Revit Outsourcing for Indian Architecture Firms: Workflow, LOD Standards & Cost BenchmarksERENDERS Editorial Staff
- 02ARCHITECTURE8 min reading timeOct 24, 2026NRI Remote Home Construction in India: The 3D Digital Twin & Milestone Quality ProtocolERENDERS Editorial Staff
- 03ARCHITECTURE11 min reading timeSep 15, 2026Climate-responsive Villa Elevation Designs in Coastal Hubs:
Studio selection
The Creator's Choice
5 picks
- 01ARCHITECTURE11 min reading timeSep 15, 2026Climate-responsive Villa Elevation Designs in Coastal Hubs:
- 02ARCHITECTURE9 min reading timeOct 29, 2026BIM & Revit Outsourcing for Indian Architecture Firms: Workflow, LOD Standards & Cost BenchmarksERENDERS Editorial Staff
- 03ARCHITECTURE8 min reading timeOct 24, 2026NRI Remote Home Construction in India: The 3D Digital Twin & Milestone Quality ProtocolERENDERS Editorial Staff